
Bean Counting
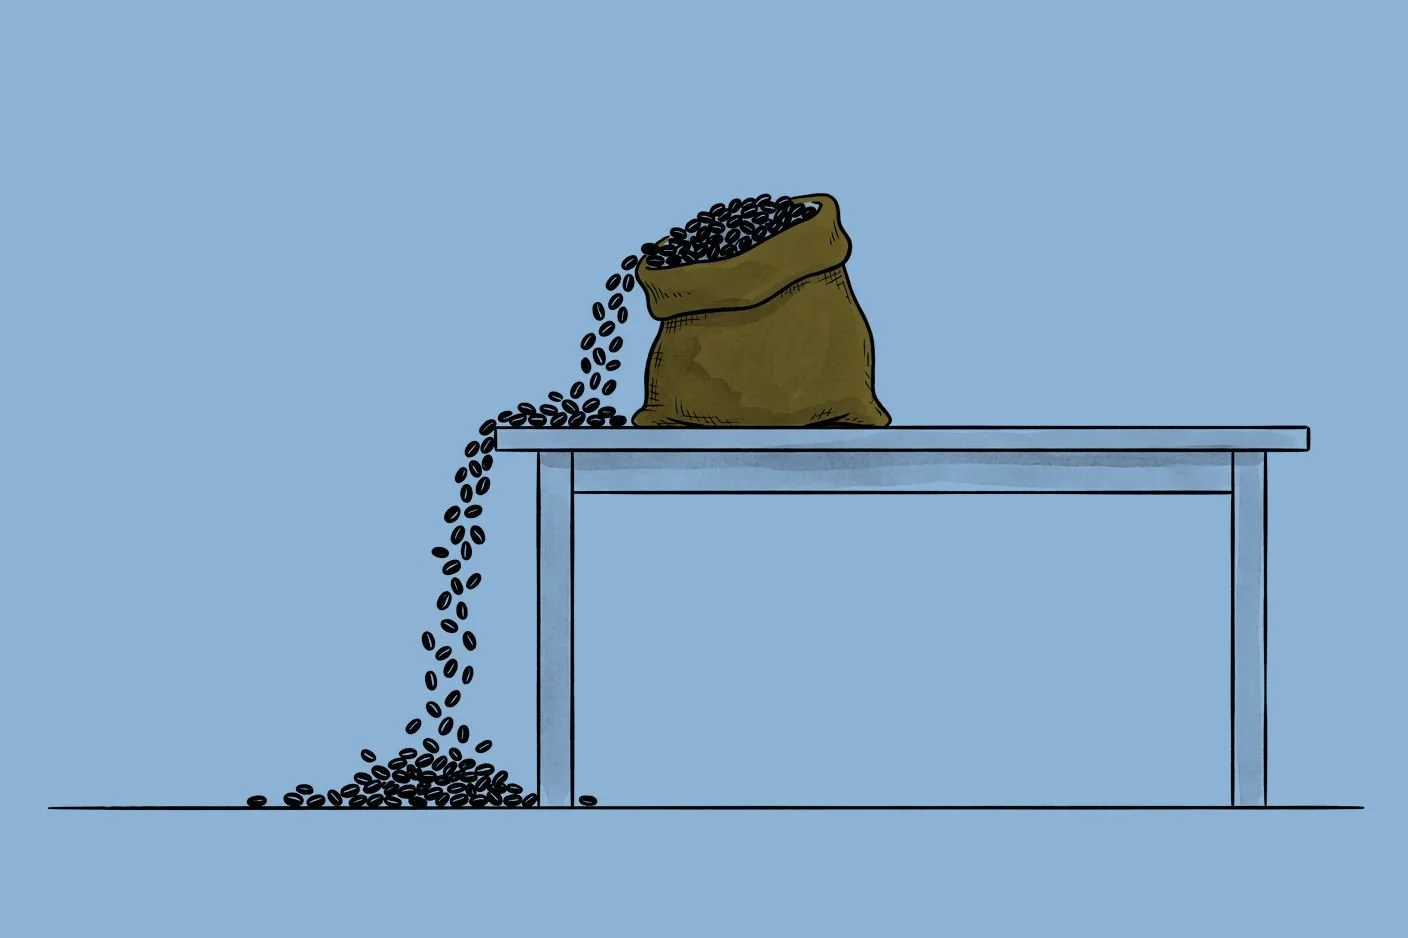
In 2025, the price of coffee beans nearly tripled. I enjoy a latte. Did the price I pay triple? Thank God, no. It went from $6 or $7 to, well, it didn't change. It turns out most of the cost of my latte isn't beans. Maybe 5% of the price trickles to the beans. Most of the cost goes to rent and labor — things that it takes to run a café. Maybe there's some profit for the café owner. Maybe.
Steamed off
Earlier this year investors poured out of software companies. Software companies write code. Code created immaculate businesses. An engineer could write a line then ship it to every customer at zero marginal cost. Those are great margins. Then came AI.
Claude Code made everyone an engineer. You didn't even need software engineers. You could just vibe code whatever solution you wanted. Why would you pay for someone else’s software? The price of generating code went to zero. The prices of software companies and software-y things dropped too. Did the future value of those companies really vaporize?
It turns out that code shares some features with coffee beans. And software-as-a-service businesses share features with cafes. Even if the price of beans goes to zero, cafés still exist. They still do stuff — steam the milk, serve vibes — that I'm not doing at home. There's still value. In software businesses there's more than just code.
Spill the beans
Here's GitLab, it's a software development platform. It serves customers developing software that favors cover-your-ass rather than move-fast-and-break-things companies. It manages source-code, delivery, security scanning, compliance logging, and, recently, AI orchestration. It handles lots of the back-office parts of coding rather than writing or selling code itself. These are things that its code-slinging customers need to do across every project.
Those customers are government agencies, banks, defense companies, etc. They're companies where the cost of software slip-ups is existential. Vibe coding won't cut it. 95% of them keep using GitLab year after year. Ultimately, they'll create more code using AI than old-fashioned organic engineers.
On top of investors developing a distaste for software-related things, GitLab changed leadership last year. Its founder, Sid Sijbrandji stepped away from the day-to-day for health reasons. It swapped in a pragmatic operator. The new CEO, Bill Staples, made some changes to improve profitability and orient around delivering value to customers. Those things don't always sound as exciting as the kind of things visionary founders say. They attract a different sort of investor base.
While Lamplighter thinks the AI panic around software is overcooked, AI has impacted the business. GitLab pivoted from charging customers by seat to charging based on usage. That caused revenue to push further into the future. Seat-based fees can be recognized in part upfront. Usage charges run through the P&L over the contract term. This makes the company look a bit worse today while it digests. The cash impact — the one investors should care about — is more neutral.
Long-term, the move aligns incentives with its customer. If GitLab delivers value, customers will use it more. Tech rag Forrester estimates GitLab's customers earn a 700% ROI. Even if it's a fraction of that, there's lots of value there for everyone.
Cold brew
The change in software coding, the change in leadership, the change in business model have scattered investors. The broad fall in software company prices earlier this year brought GitLab shares further down. The company's turned a corner on profitability. It's won more new business. It's carved a durable place for itself in customers operations. Shares offer investors an opportunity to enjoy this blend of circumstances for an enticing opportunity.
Disclaimer: None of this is investment advice. It's meant to illustrate ways LCM thinks about investing. Things that LCM decides are good investments for LCM and its clients are based on many criteria, not all of which are covered here. Some or all of LCM's ideas may not be suitable for other investors. LCM does not recommend investing either long or short any position mentioned. LCM may own positions in some of the companies mentioned. Some of its ideas will lose money — investing entails risk. See full disclaimer here.